MasterSearch

Showing posts with label Finance. Show all posts

Wednesday, January 23, 2013

#China Narrowly Averts #Credit Bubble Pop With Latest Government Bailout Of First Domestic #Bond #Default | Zero Hedge


See the whole article here:  China Narrowly Averts Credit Bubble Pop With Latest Government Bailout Of First Domestic Bond Default | Zero Hedge


Monday, July 25, 2011

S&P Returns since 2001 Featured Charts

S&P Returns since 2001 Featured Charts


dshort Featured Charts

Share this|
________________________ The MasterBlog

Tuesday, May 17, 2011

Gold and Financials


Gold and Financials
From Richard Russell:

The best comment on gold that I have seen comes from my old friend, Ian McAvity in his latest mailing of Deliberations : "The latest run on gold came from the early April breakout through the area around 1425, which becomes a logical support area for a corrective pullback. Gold first crossed $1400 in November and fought it for 21 weeks. The prior significant breakout was through the $1260 level, first touched in early December, 2009, and penetrated 22 weeks later with more follow-through, and finally resolved with conviction in September, 2010, 42 weeks after the first touch.
"Measuring swings with intra-day Comex extremes, this run gained $268 in 14 weeks from the late January low to the $1577 high this week. The prior two rallies (to $13451 & $1262) gained $275 in 19 weeks and $220 in 20 weeks. With recent runs and corrective phases running about 20 weeks in duration, it's possible this run could extend further. But the blowoff and turbulence in silver in the past two weeks, and the lousy relative behavior of the gold and silver shares prompts me to speculate an intermediate top may have been put in, and we may need another period of 20 weeks or so to correct, digest, cool off and set-up the next leg."

Below, a chart covering two years of gold action illustrates gold's repeated periods of correction, a period of consolidation lasting roughly 14 to 20 weeks, and then an upside breakout to new highs. The current situation may be a repeat of this same action that has occurred repeatedly over the last two years.


Russell advice -- Be patient with your gold, and sit tight.

Lowry's statistics remain bullish. My PTI remains bullish. The Dow and the Transports recently bettered their April highs, which (from a Dow Theory standpoint) is bullish. But I remain nervous regarding this market. One reason is seen through the chart below.
This is the ETF for the Financials, and it has formed a bearish descending triangle. It's hard to envision this market as being healthy with the financials in such poor shape.


I didn't fully trust the ETF above so I looked for confirmation, and I found it. Below we see the NYSE Financial Index, which contains ALL the financial stocks on the NYSE -- banks, S&Ls, small loan companies -- and this chart looks no better. It's hard to see the market climbing without the financials. The financials have been one of the big success stories since the 2009 lows. The Financials now appear to be under distribution. Best, we keep an eye on them.


Share
_______________________________________
Check it out on The MasterCharts

Friday, May 06, 2011

Commodities VaRy extreme right now

Commodities VaRy extreme right now

Hark — the standard deviation devils sing (again).
As Reuters columnist John Kemp pointed out yesterday, recent swings in the commodities complex have produced some impressive probabilities figures. The kind you can wheel out in dinner party conversation. For instance, front-month Brent crude futures sank almost $12 per barrel (or over 9 per cent) on Thursday, leading the market down from over $120 at the start of the day to under $110.
That's a price change of more than four standard deviations — which is a statistical way of saying it's something that should be seen on average only once in every 63 years, assuming a normal bell-curve distribution. Kemp also points out that at times on Thursday the move also approached five standard deviations — something which should only occur once every 7,000 years.
Now, who wants to bet that algorithmic trading models, or banks' risk management ones, don't extend to this kind of (rare-ish) movement? After all, these models tend to be based on recent history and banks rarely feel the need to take into account extreme events which have never happened. Such was most famously the case, of course, in credit risk management ahead of the subprime crisis.
It's certainly the thinking behind graphics like the below — from Reuters on Thursday:
That's Value-at-Risk (VaR) for major US banks. In words it would mean, for example, that there's a one in 20 chance that Goldman Sachs' daily commodities trading net revenues would fall below expected daily trading net revenues by an amount at least as large as the reported VaR — or about $37bn in the first quarter. Note that VaR predictions, however, tend to be a poor predictor of actual losses. And banks have the ability to ignore them somewhat, as Goldman Sachs did during the subprime crisis.
Here's Kenneth Posner in his book, Stalking the Black Swan:
The company shorted the ABX index just like the hedge fund in Chapeter 4, earning more than $1 billion in profits during 2007. During this period, senior executives were monitoring the value-at-risk … associated with the firm's mortgage position, as well as grilling the mortgage traders on the rationale for their bets. On separate occasions, the executives forced the traders to downsize their positions, even though the trades were profitable, in order to keep the VaR in check. At other times they allowed the VaR to rise to an all-time high.
Given Goldman Sachs called for Brent to return to $105 a barrel just three weeks ago — much to the amusement of some other banks (likeBarclays Capital) — we're guessing there won't be too much Goldman hand-wringing over size able commodities VaR. If the bank followed its own published advice, it should be well-positioned (once again).
Barclays, incidentally, is one of the few European banks that does not break out its quarterly commodities VaR.


Tuesday, March 15, 2011

We’ve Taken Out All Trendlines

We’ve Taken Out All Trendlines

Things are getting VERY ugly in the financial markets. Indeed, we’ve taken out virtually every trendline that supported the markets from the 2008 Crash.
First off are the emerging markets: trendline broken and retest failed.
Same goes for THE commodity play: Brazil:
And the “growth miracle” China:
Here in the US, the S&P 500 has taken out the trendline that supported it from the end of September onwards:
The US Dollar has ALSO taken out its long-term trendline:
In plain terms, the financial system is RED ALERT. The question now is if additional liquidity can prop this giant house of cards up anymore.


We’ve Taken Out All Trendlines

_______________________________________
Check it out on The MasterCharts

Friday, February 18, 2011

Banks and investment firms have rebounded fastest since March 2009 lows

Chart of the day: Barclays and Lloyds soar since lows

Kit Chellel
18 Feb 2011
4068036725_c300,200,50,50,100.gif

How financial firms in the FTSE100 have performed since the lowest point of the crisis
Two weeks from today is the second anniversary of one of the darkest moments of the financial crisis, when the FTSE 100 fell to a new low and Barclays shares were going for as little as 81p.
On that day, March 3, 2009, the 100 largest companies in the UK were worth less than they were when Tony Blair was elected in 1997.
The FTSE 100 has not hit such depths since, and an equities rally over the past few months has seen the index recover to somewhere near two-year highs.
Figures compiled by Financial News show that banks and investment firms have rebounded fastest, albeit from a lower level.
An investor who bought shares in the 10 financial firms (excluding insurers) currently in the FTSE 100 back in March 2009, would have seen a return of 149% in those two years, based on prices on Thursday morning.
This compares to an average of 73% across the FTSE 100 index.
An investor who backed Barclays would have done even better. The bank, which avoided a government bailout by tapping up Middle Eastern oil money, has risen a staggering 311% in the same period.
Lloyds is up 205% and private equity group 3i 182%.
The worst performer was investment group Alliance Trust whose shares rose 58.8%, which is below the FTSE average.
Second from bottom among the financial firms was Man Group which has been beset by problems since the crash. The listed hedge fund has seen half its assets under management pulled out by investors since the start of the crisis. Despite this, its shares have still gained 92 per cent between March 2008 and now.
The share gains achieved by banks are all the more impressive given that Barclays, HSBC, Lloyds and RBS all carried out multi-billion pound share issues to recapitalise following the crisis, diluting the value of stock.
The FTSE 100 index closed at 6087.38 yesterday, helped by strong performance from Lloyds TSB (up 2.9%) and RBS (up 3.8%). However the index remains some way below the pre-crisis peak of 6721.60 on September 31, 2007.


http://www.efinancialnews.com/story/2011-02-18/barclays-and-lloyd-best-performing-shares-since-crisis-trough?utm_source=twitterfeed&utm_medium=twitter

Friday, December 17, 2010

Market timing - European Financial Risk Breaks Out- Sell signal?

 Market timing - European Financial Risk Breaks Out- Sell signal?

CONCLUSION: As our mark Steele points out below, European corporate financial risk is breaking out...this was a SELL signal last spring. Yet this time so far, there has been a definite lack of contagion. The elastic band is being tested.....

Relative Strength Filter
December 17, 2010
Research Comment
Mark Steele
(416) 359-4641
Assoc: Tiberiu Stoichita/Rahul Muralidhar
European Financial Risk Breaks Out
CLICK HERE for a printer friendly version of this report including research disclosures.


Figure 1: European Financial (Markit) and European Prime Broker (our .PrimeEU) Financial Default Risk; FTSE Global Banks


Source: BMO Capital Markets, Bloomberg, Thomson, Markit


· This morning, European corporate financial default risk breaks to the upside – Figure 1.

o This was a sell signal in the spring.

o This was a sell signal in November.

o This is a caution signal now.

§ What is different?

· If you carve out the too-interconnected-to-fail European prime brokers (our .PrimeEU index), and overlay this on the European Financial default risk chart, you see a definite lack of contagion.

o The core is solid.

o The caution, of course, comes as we assume that if overall European financial default risk continues to rise, then there will be a moment when the elastic band connecting the two (Figure 1 top) will force the too-interconnected-to-fail institutions into the fray.

§ Today, we get off with just a caution, but a big caution.

Sunday, December 12, 2010

Gold Market Forecasting and the Magnetic Power of the $2,298 Target Price

Gold Market Forecasting and the Magnetic Power of the $2,298 Target Price-- Posted Sunday, 12 December 2010
| Source: GoldSeek.com

By David Knox Barker

The Long Wave Dynamics approach to Fibonacci drill-down price grids in any market index such as the S&P 500 and European S&P 100 generates extraordinary actionable market intelligence for investors and traders. Creation of the drill-down Fibonacci grid approach to market analysis is the result of decades of market cycle research and studying the market timing of a number of cycle masters. The goal was a formula timing plan for buying low and selling high based on cycles that works for both investors and traders.

Fibonacci Dynamic Web methods demonstrate how every Fibonacci price grid is driven by three ranges, 1) Solitude 0%-38.2%, 2) Normal 38.2%-61.8%, and 3) the Frenzy range of 61.8%-100% of any Fibonacci price grid. Prices often turn exactly on the golden and inverse golden targets in the Fibonacci price grids.

Working with major indexes such as the S&P 500, the 1982 intraday low and the 2007 intraday high provide the perfect Level 1 grid range to begin the Fibonacci grid drill-down process. Other major markets do not offer as much history, but they provide enough for a solid Level 1 price grid. However, the gold market has been making all time highs on a regular basis, so a clear Level 1 price high is not available.

This is where things get interesting in terms of very recent gold market price action. In order to generate a Level 1 price high to begin the Fibonacci grid drill-down process, you have to use a past major move as a key move in a full grid move that remains in the future. Yes, what I am suggesting is that you must look into the future and see an important top in the price of gold.

Tuesday, November 30, 2010

Your One-Stop Guide To Frontrunning Monday's Double POMO | zero hedge

Your One-Stop Guide To Frontrunning Monday's Double POMO

Friday, September 17, 2010

CNBC Market Blah, Blah ..Friday Look Ahead: Tech a Focus for Stocks Friday, as Gold Dazzles Investors

Friday Look Ahead: Tech a Focus for Stocks Friday, as Gold Dazzles Investors

Published: Thursday, 16 Sep 2010 | 9:10 PM E
By: Patti Domm
CNBC Executive Editor
Some good news from the tech sector could be a positive for stocks Friday.
Outside the New York Stock Exchange in lower Manhattan.
Photo: Oliver Quillia for CNBC.com
Outside the New York Stock Exchange in lower Manhattan.

Both Oracle and Research in Motion reported strong earnings after Thursday's bell. Separately, Texas Instruments boosted its $0.12 dividend by a penny and said it would buy back another $7.5 billion shares. All three stocks were higher in after-hours trading.
Stocks Friday morning could feel the effect of the quadruple expiration of futures and options. Traders expect the expiration to be low key at the open, and if anything, the impact should be slightly positive.
CPI, at 8:30 a.m., is expected to show a 0.3 percent increase in August consumer prices. Consumer sentiment is expected to improve slightly to a reading of 70, from 68.9 last month, but economists say the strong performance of the stock market this month could push that number a bit higher. August's sentiment reading was the second lowest of the year. Consumer sentiment is released at 9:55 a.m.
Stocks drifted on both sides of the unchanged mark Thursday. The Dow ended up 22 at 10,594, and the S&P 500 was off less than a half point at 1124.  The dollar weakened against the euro, and dollar/yen was barely changed after the Bank of Japan intervened to curb the yen's rise Wednesday.
"This intervention might have higher chances of succeeding, assuming we continue to see relatively acceptable U.S. economic data. That's the critical thing," said Boris Schlossberg of GFT Forex. "...as long as the idea of double dip keeps receding, Treasury yields should stabilize and go back up and that will be critical to dollar/yen."
On the other hand, if we see the 10-year yield move to 2.5 percent, or dip below 2.5 percent, I don't think any amount of money will stem the (dollar) decline," he said.
Barry Knapp, chief equities portfolio strategist at Barclay's, said the initial stock market reaction after a big intervention is often a short-term decline. "For the first couple of days, the market goes down a little bit..the first reaction is to look at the dollar," he said.
The view is "if the dollar is going up, that's bad for earnings, so sell it. Dollar's going down, that's good. That's a very simplistic approach. I don't think it's right at all," he said. "If you look back at 2003, when the Japanese were intervening dramatically, the initial reaction was that the stock market sold off, and then it regained its footing."
Knapp said the intervention at that time was about $360 billion, and he estimated this round could total $250 billion. The BOJ was reported to have bought more than $20 billion Wednesday.
"If somebody puts $250 billion into the markets, event though that money won't be buying riskier assets, it can trigger an effect," he said.
The impact on Treasurys could also be noticeable, he said. Traders have been speculating the Japanese will park their dollar holdings in shorter duration Treasurys. "Initially the Treasury curve steepens, but then that tends to drive investors who were in 2s and 5s to extend out the curve and it starts to flatten. Then it triggers a whole position rebalancing."
All that Glitters
Gold continued to dazzle investors Thursday, scoring its second record settlement of the week. Investors are betting it could try to break the $1,300 level, maybe even as early as next week depending on the outcome of the Fed's meeting Tuesday.  Gold Thursday rose about a half percent to settle at $1273.80.
Gold has faced some high-profile criticism this week, including from investor George Soros who called it a bubble. "If you think about a world where every major country is trying to find a way to devalue its currency, gold looks pretty good in that environment. Personally I think the dollar is going down more. There's lots of reasons why gold will continue to rise. I don't know if I'd buy it, but I know I wouldn't short it," Knapp said.
 http://www.cnbc.com/id/39223276

Sunday, September 05, 2010

A 7 Million Increase In US Population Results In A Labor Force... Decline? Why The US Has Really Lost 11.2 Million Jobs This Recession

A 7 Million Increase In US Population Results In A Labor Force... Decline? Why The US Has Really Lost 11.2 Million Jobs This Recession

Links:
[1] http://www.zerohedge.com/sites/default/files/images/user5/imageroot/Population Growth and Labor Force_1.jpg
[2] http://www.zerohedge.com/sites/default/files/images/user5/imageroot/Population Growth and Labor Force 2.jpg

A 7 Million Increase In US Population Results In A Labor Force... Decline? Why The US Has Really Lost 11.2 Million Jobs This Recession

Wednesday, September 01, 2010

Demonised ‘algos’ push the surge in FX trading - FT.com

Oh, poor "Demonized Algos" !!!

Demonised ‘algos’ push the surge in FX trading

By Jennifer Hughes, Senior Markets Correspondent
Published: September 1 2010 00:04 | Last updated: September 1 2010 00:04
Since the infamous stock market “flash crash” of May 6, high-frequency, or algorithmic, trading has been unwillingly dragged into the political and regulatory limelight.
forex-trading-graphicSo far, however, attention has focused on the role of these high-speed traders in the equity market. Outside the glare of that publicity, it is less well known that on May 7, FX trading volumes reached records, straining the plumbing of these markets.
Some participants argue these strains were partially caused by algorithmic, or algo, traders.
Exactly how much of this can be attributed to algo trading is unclear. However, there is no question that high-frequency traders are a fast-increasing force in FX markets, which is sparking a fierce debate as to their value to the market.
On Tuesday, the Bank for International Settlements reported that average daily turnover in the FX market has jumped 20 per cent in the past three years to $4,000bn a day. Its survey was taken in April, so missed the May spike, which related to the eurozone sovereign debt crisis.
The BIS-reported gains were led by a near 50 per cent leap in spot trading – deals for immediate delivery – to $1,500bn a day. This jump was powered by increased activity from “other financial institutions”, a group that includes hedge funds, pension funds, some banks, mutual funds, insurance companies and central banks. This will also include algos.
While all categories of “other” could have increased their trading, it is likely a significant proportion was driven by algo traders, who favour the deep, liquid spot markets and particularly currency pairs such as eurodollar and dollar-yen, which between them account for 42 per cent of all currency trading.
The question for the FX market is whether high-frequency dealers improve the market by adding liquidity, or whether they are instead merely price takers who contribute little.
“Algos have been demonised, but they’re an important part of the growth story,” says David Rutter chief executive of Icap Electronic Broking, which runs EBS, the main FX interbank trading platform. “What we’ve found is that they add pressure at each price point so that instead of getting big price gaps on shocking news, trade is more orderly.
“With FX, there are a lot of other flows such as global trade, so there is good underlying liquidity that the algos can enhance.”
Algos initially appeared in FX markets almost a decade ago, attracted by the deep liquidity and increasing use of electronic trading. They were generally welcomed, particularly by banks looking to build their prime brokerage businesses. However many banks soon grew disenchanted when they found the fast-moving shops were profiting from banks’ own slow systems by exploiting brief, tiny price differences between rival platforms.
Some banks went as far as ejecting offenders from their platforms but banks’ views have since become more nuanced. They have generally reached an accommodation, helped by technological improvements which make it easier to monitor client dealings and offer client-specific prices.
“The facts are that algos have made the markets more efficient and have helped ensure there’s one virtual price,” says Jeff Feig, global head of G10 FX at Citigroup. “They do cause banks to be smarter and we’ve had to work harder to be more efficient, but that’s ultimately to the advantage of the end user.
“I think that to some extent, algos have pushed banks and the result has been enhanced transparency and increased liquidity.”
Algos mean many different things in the FX market. While high-frequency traders are the best known – typified by one senior banker as “five smart guys in a room in New Jersey,” – banks are increasingly adept at developing their own algorithms to make their internal FX deals more efficient. These “internalisation” trades too will have provided a boost to the BIS numbers.
Most players say algos are now a fact of life in currency markets.
Unlike the equity market, which is split into hundreds of stocks, they believe the FX world’s focus on a relatively small number of currency pairs means it would be far harder for a single group of participants to move the market significantly, intentionally or otherwise, as some watchers fear happened during the “flash crash”.
“Also trading can happen anywhere there’s an electronic execution system and a volatile market,” says Alan Bozian a former FX banker and now chief executive of CLS Bank, the FX settlement system. “The question is, which markets adapt well and I don’t think it’s necessarily the stock market.”
FX markets have proved generally good at adapting. Systems such as CLS, introduced years before the financial crisis, have helped minimise settlement risk and since May, participants have been working again to improve their processing systems to cope with increased volume.
Significantly, for a market that is very much built around a hub of big banks, the BIS report showed that, for the first time, interaction of the main banks with “other” financial institutions overtook trading between themselves.
This could be a pointer to the market of the future, where banks are likely to remain the hub, but as much for their trade processing abilities as for their liquidity.
This would allow the winners to build profitable volume without taking on huge trading risks – suiting the current regulatory mood.
“The banks want to continue being the price providers, but they’re getting much more interested in the infrastructure and improving that,” says Mr Bozian. This evolution is likely to apply to high-frequency trading too.
Mr Rutter believes algos are only in their “late teens” in terms of development. “The early algo trading was about super-fast dealing and chasing inefficiencies. That’s largely gone,” he says.
“Now its about math and science being thrown at the market – there’s a rich pool of data and I think we’ll see algos evolve so its not just about milliseconds, but about longer-term predictive math.”
"FT" and "Financial Times" are trademarks of the Financial Times. Privacy policy | Terms


FT.com / Currencies - Demonised ‘algos’ push the surge in FX trading

Share
-- The MasterFeeds

Tuesday, August 31, 2010

IRS Hiring Special Agents for Criminal Investigation Division - Finance Career Management, Finance Career News - fins.com


IRS Hiring Special Agents for Criminal Investigation Division - Finance Career Management, Finance Career News
fins.com


Come one, come all: The IRS is hiring for one of its prime divisions.
The agency expects to get $5.1 million to spend on hiring for its Criminal Investigation Division -- though an agency spokesman could not say exactly how many the IRS is looking to hire.
A recently-released report from the Treasury Inspector General for Tax Administration (TIGTA) that assesses the Division's performance states that special agent staffing has increased 4.1% from last year, from 2,617 to 2,725. But the difference of 108 positions represents the net between 312 newly hired agents and the loss of 204 experienced agents. Overall, the number of field special agents has decreased 10.2% since 2004.
This new hiring comes in the wake of last year's push for 800 new employees to scour the world in search of American tax evaders.
The turnover has resulted in fewer case completions than in previous years. Last year, TIGTA expressed concerns that the Division would fail to "reduce the pipeline inventory." That worry was justified. Even though the Division reduced its completion goal from 4,000 to 3,900, it still came up 52 investigations short in 2009.
As the recent kerfuffle between U.S. and Swiss authorities over the transfer of tax data indicates, the premium placed on routing out international tax schemes has reached an all-time high, and the IRS needs agents around the world to act as gumshoes. According to the report, "the international initiative will require increased hiring and include a broader range of cases and sharply increased presence in other countries."
While an IRS spokesman could not give a full outline of the hiring initiative, he did highlight some of the necessary qualifications that can be found on the IRS' website:

-- Younger than 37, unless you've served in a federal law enforcement position before.
-- Prime physical condition (you'll be tested on it).
-- Gun-shooting experience.
If you're comfortable with all of the above and you like the sound of Special Agent [Your Name Here], you may want to consider applying.


IRS Hiring Special Agents for Criminal Investigation Division - Finance Career Management, Finance Career News - fins.com: "IRS Hiring Special Agents for Criminal Investigation Division
By Julie Steinberg"

Share
_______________________________________
Check it out on The MasterCharts

Monday, August 30, 2010

MasterTech: RIM = RIP ? Research in Motion Continues Its Downwa...

RIM = RIP ?

Sounds like TAPS in the background....

Between the pressure on the corporate side of the business from governments who want access to all the data passing through the blackberries in their countries, and the real risk of migration by consumers to the iPhone and Android OS, the future doesn't look too bright RIM...

Below are charts.  The whole story can be seen on The MasterTech Blog or directly on zerohedge.com.
As Research in Motion Continues Its Inevitable Downward Descent In Both Equity Value and Market Share, Investors Should Tweak Their Assumptions Accordingly
Research in Motion's recent equity share decline stems not only from market share loss, but from the apparent lack of a clear cut and believable plan to stem that market share loss.

Research in Motion, is still currently the market leader in terms of share, but is losing both demonstrably and rapidly in new users. As a matter of fact, if the recent historical trends persist, this is the last quarter that RIM will be able to claim the top of the market title as Android looks well situated to claim that crown.


As can be seen from this chart, Android is just about there. Apple will probably show better numbers in Q3 with additional evidence of iPhone 4 adoption as well.
So, although RIM is looking quite cheap now, it is quite possible for it to look much cheaper. The question is how does this market share loss factor into its equity valuation.

MasterTech: Research in Motion Continues Its Inevitable Downward Descent In Both Equity Value and Market Share

_______________________________________
Check it out on The MasterCharts

Wednesday, August 25, 2010

Richard Russell's Daily Letter

August 24, 2010 - "I place economy among the first and most important virtues and public debt as the great danger to be feared. To preserve our independence, we must not let our leaders load us with perpetual debt. We must make our choice between economy and liberty, or profusion and servitude." Thomas Jefferson. 
...................................................................................


Throw a tennis ball up in the air, and it will lose upward momentum as it rises. At some point upside momentum will completely fade, and the ball will stand still in mid-air. After standing still for a brief moment, the ball will head back toward earth.


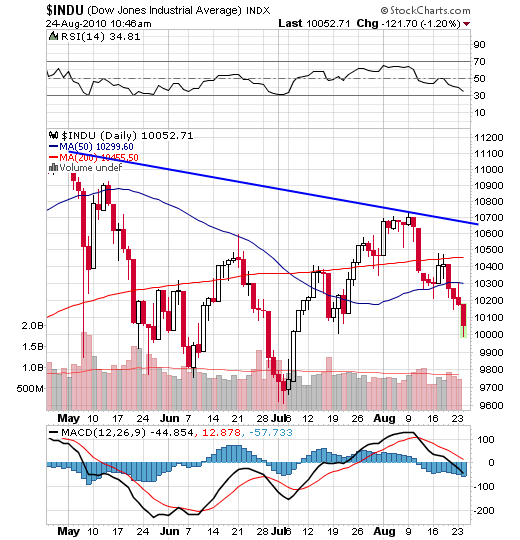
Somehow, I get the same feeling about the stock market. The market gained initial upside momentum as it surged up from its July low. By early August the market had lost upward momentum. For seven days the Dow moved sideways as if suspended in midair. On August 11, the market suddenly plunged 265 Dow points, and in so doing it fell out of its sideway trading range. From there, the Dow whipped back and forth, and by August 19, the Dow had fallen bearishly below both its 59-day and 200-day moving averages.


The daily chart below shows us what the Dow looks like now. Note that RSI is heading down, and MACD has turned negative. At the same time, the Dow is situated below its 50-day moving average, and the 50-day MA, in turn, is below its (red) 200-day MA. Finally, note that the Dow has assumed the form of a head-and-shoulders top that has now broken down. In all, a classic set of bearish relationships. 


I'm including a P&F chart of the Dow below. Note the latest red column of X's which just plunged below the 10150 box and below the rising blue trendline. According to this P&F chart, we received a "sell signal" this morning when the Dow broke below the preceding column of 0s and below it rising blue trendline. The P&F "projection" is that this break should take the Dow down to the 9750 box.


Incidentally, there is no shortage of "distribution days." The latest score for the last two weeks is -- 6 for the S&P 500, 5 for the Dow, 5 for the NASDAQ and 5 for the NYSE Composite. That's far too many, and it implies heavy institutional selling.
Yesterday, I wrote about the Treasury bonds. Every "smart" trader and investor has rushed into Treasury bonds as the ultimate save-haven area. I believe Treasury bonds and high-grade corporate bonds are in a bubble. There are just too many believers in bonds as the ultimate safe place to be. 


When everybody piles onto one side of the ship, the ship lists. And just as quickly, everybody rushes to the other side of the ship. That's where I think we are with bonds. 


The weekly chart below follows the 30-year T-bond. RSI tells us that the bond is overbought. The full stochastics at the bottom of the chart confirms that the bond is overbought. And the blue histograms are slanting downwards towards zero. All in all, I don't like the looks of the bonds. Any hint of rising interest rates could send the bond market off the edge of the popularity cliff. 


Gold -- I took today's stock market sell-off as an indication that business will be rotten in the months ahead. Rotten business will put pressure on the Fed to print, print, print. Wide open quantitative easing will put pressure on the dollar, and this, in turn, will put UPWARD pressure on gold. And gold may have started to discount that situation today.


Share |
_______________________________________
Check it out on The MasterCharts

ShareThis

Gold or Silver?

MasterSearch